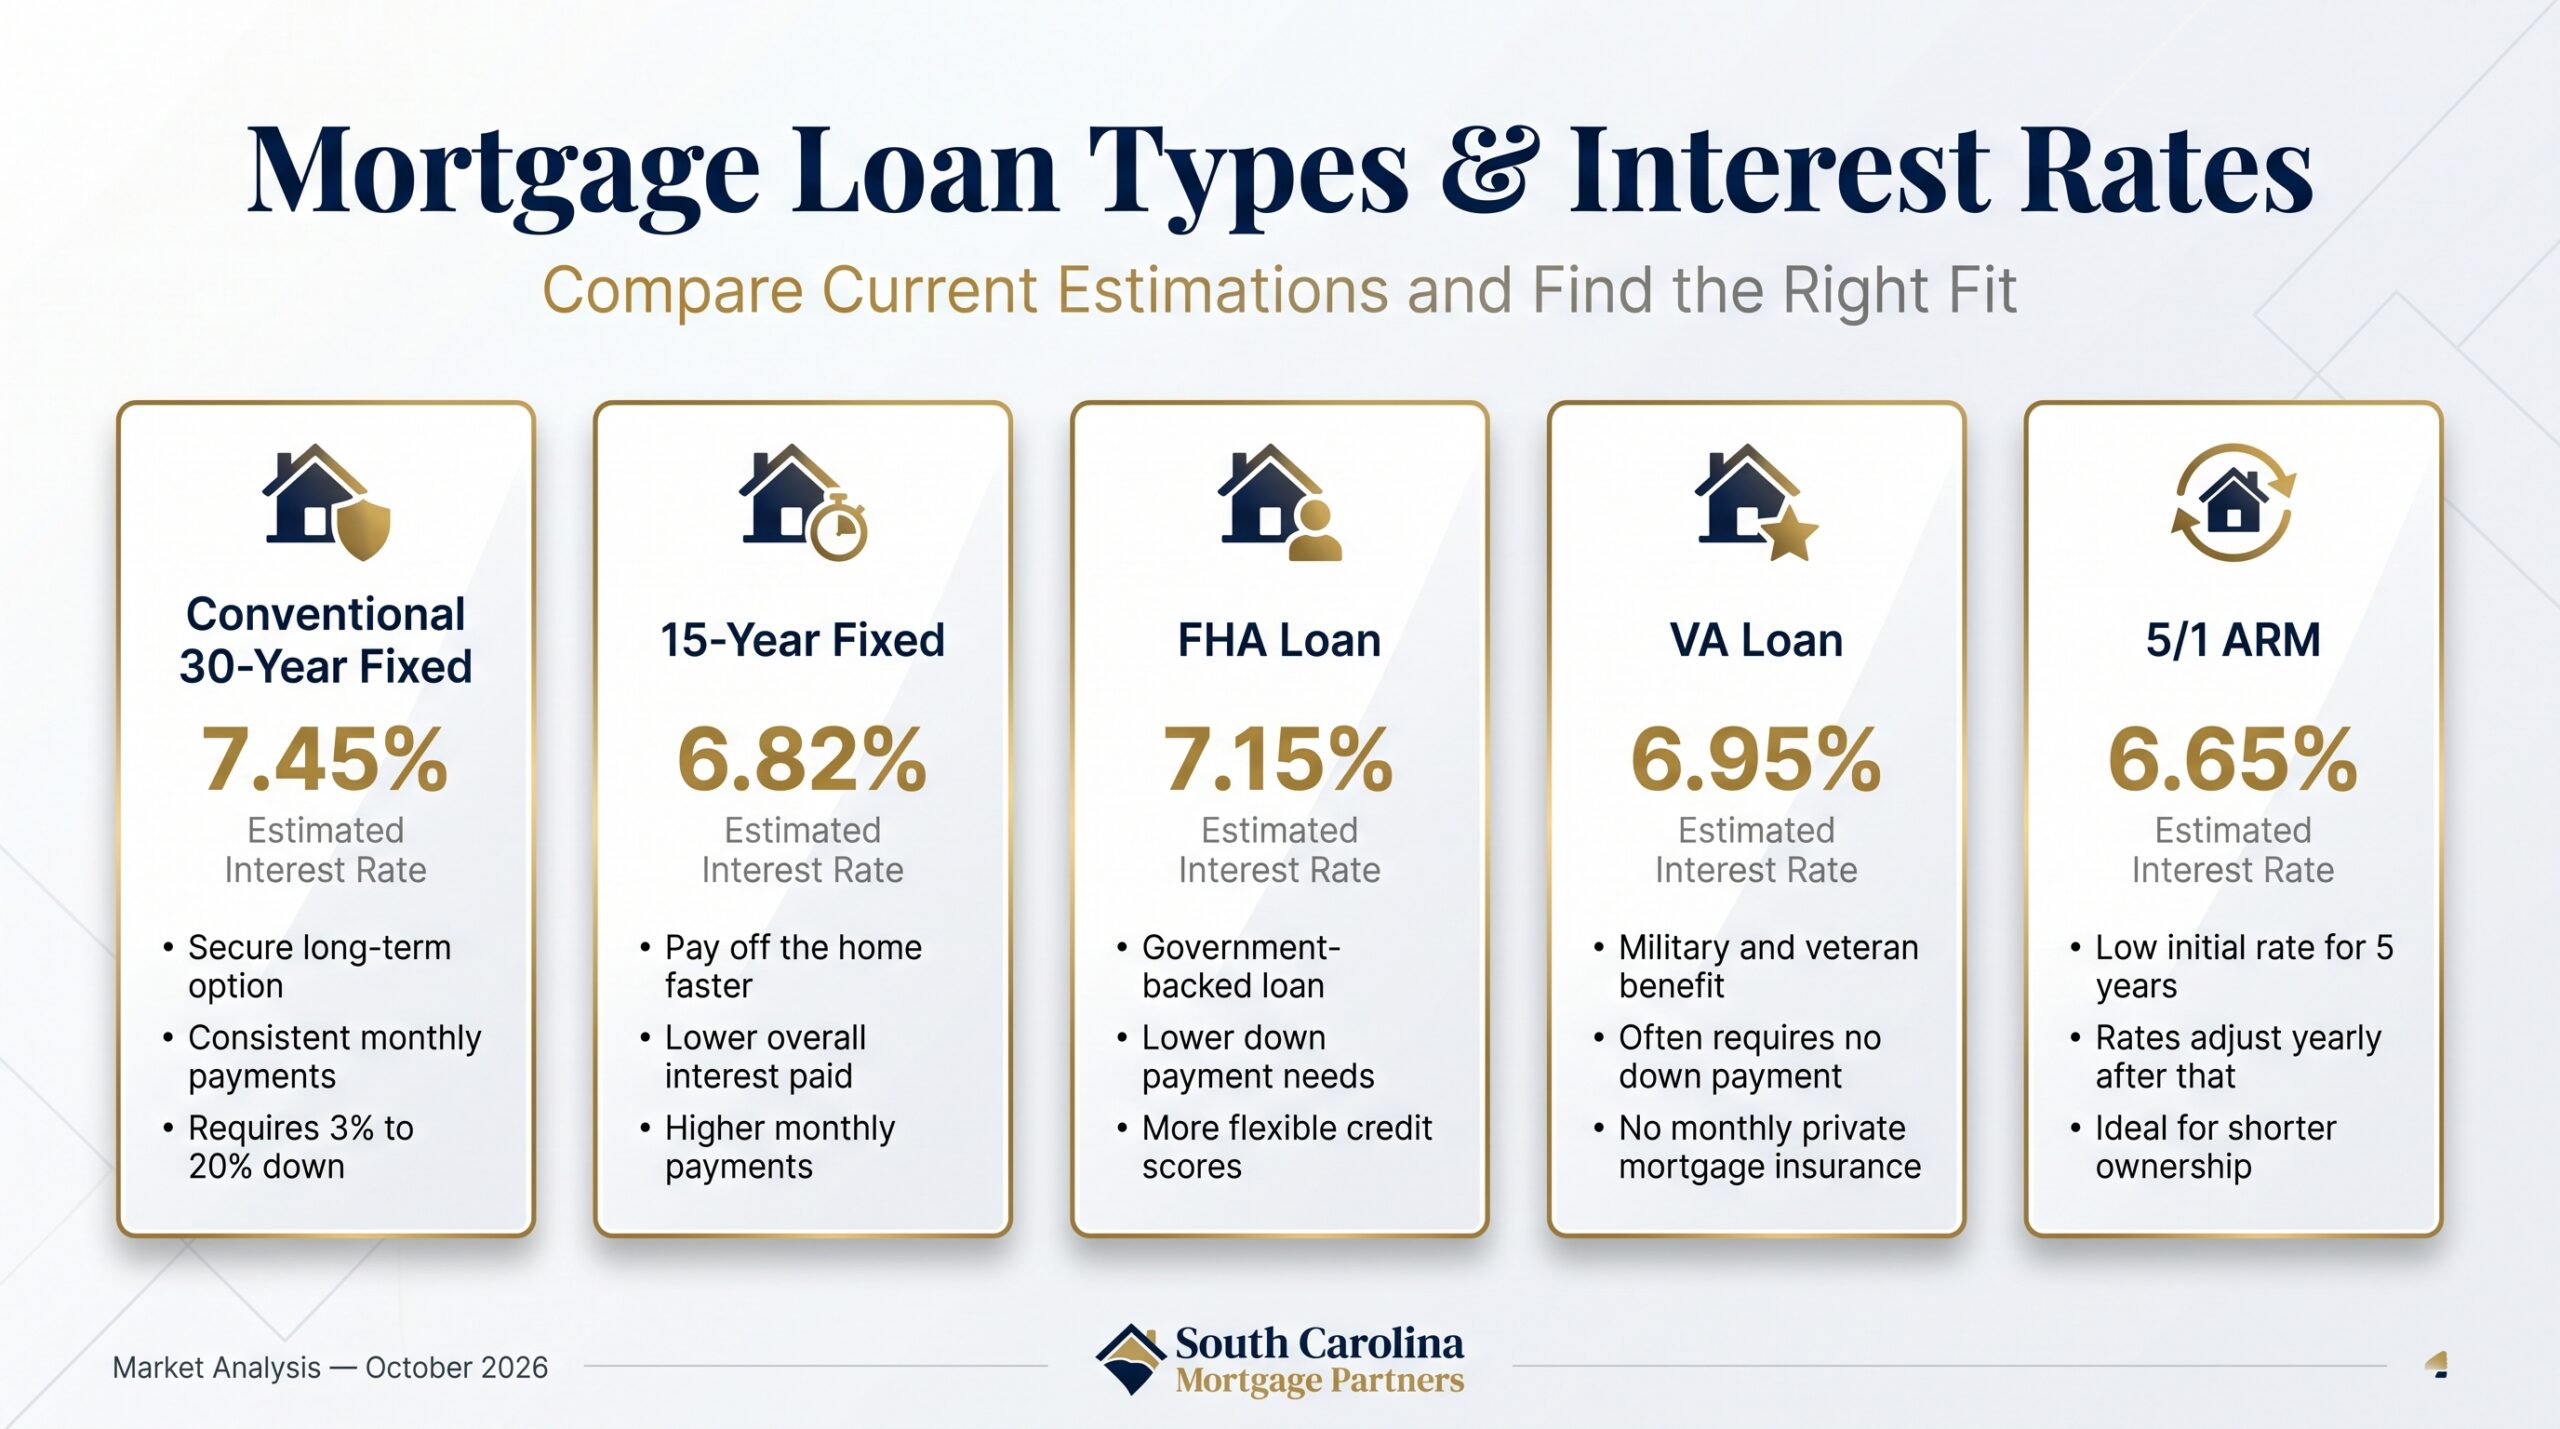
What are mortgage interest rates this week in Charleston, and how do they affect your home buying plans?
As of October 15, 2026, the national 30-year fixed mortgage rate averages 7.40% per Freddie Mac’s PMMS. If you are buying in Charleston, Mount Pleasant, or Summerville, that number has real consequences for your monthly payment and purchasing power.
Why This Matters Right Now in the Charleston Market
Let me be straightforward with you: rates have moved fast, and if you are actively shopping for a home in the Lowcountry, you need to understand what is happening this week, not last month.
The 30-year fixed mortgage rate jumped from 7.03% on September 24, 2026, to 7.28% on October 1, and then to 7.40% as of October 15, 2026, per Freddie Mac’s Primary Mortgage Market Survey. That is roughly 37 basis points of increase in just three weeks. Whether you are eyeing a new construction neighborhood in Summerville or a family home in Mount Pleasant, this shift changes the math on what you can comfortably afford.
With 7 years of experience helping buyers navigate exactly these kinds of market shifts, I can tell you that rate volatility like this is when having real data in front of you matters most. So let me walk you through exactly what I am seeing and what it means for your next move.
How October’s Rate Surge Impacts Charleston Home Buyers
Here is the trajectory in plain numbers so you can see just how quickly things have shifted:
- September 24, 2026: 30-year fixed at 7.03% (per Freddie Mac PMMS)
- October 1, 2026: 30-year fixed at 7.28% (per Freddie Mac PMMS)
- October 15, 2026: 30-year fixed at 7.40% (per Freddie Mac PMMS)
And for those considering a shorter-term loan:
- October 1, 2026: 15-year fixed at 6.60% (per Freddie Mac PMMS)
- October 15, 2026: 15-year fixed at 6.71% (per Freddie Mac PMMS)
So what does a rate like 7.40% actually feel like in your budget? On a $400,000 loan amount over 30 years, your principal and interest payment comes to approximately $2,764 per month. Back in early March 2026, when the 30-year hit its calendar-year low of 6.00% per Freddie Mac, that same loan would have cost approximately $2,398 per month. That is a difference of roughly $366 every single month, or about $4,392 over the course of a year.
I share those numbers not to cause panic, but because when I sit down with buyers relocating to Charleston from out of state, they often ask me, “Did I miss the window?” The honest answer is that rates have climbed meaningfully since spring. But that does not mean the opportunity is gone. It means you need to be more strategic about your approach.
The Year-Over-Year Picture for Mount Pleasant and Summerville Buyers
To put today’s rates in even sharper perspective, consider where things stood just one year ago. As of October 15, 2025, the 30-year fixed averaged 6.27% and the 15-year averaged 5.52%, per Freddie Mac. Today, the 30-year sits 113 basis points higher and the 15-year is 119 basis points higher.
What does that tell you? It tells you that the affordability picture has shifted substantially in 12 months. If you started your home search for neighborhoods in Mount Pleasant like Old Mount Pleasant, Belle Hall, or the Rifle Range Road corridor last fall, you were working with a different set of numbers. The home prices may have changed too, but the borrowing cost alone has taken a meaningful bite out of purchasing power.
For first-time buyers in Summerville, where homes in communities along Jedburg Road or in Cane Bay and Nexton tend to carry more accessible price points, the rate increase hits proportionally harder. You may have less equity from a prior sale to offset higher borrowing costs, so every fraction of a percentage point on your rate matters more.
What I tell my clients is this: do not compare today to the rates you saw in someone else’s listing from February. Compare today to where rates might be in February of next year, because nobody has a crystal ball for that. Making decisions based on the market you are in, not the one you wish you were in, is how smart buyers move forward.
Should You Consider a 15-Year Fixed in the Charleston Market?
The 15-year fixed rate at 6.71% as of October 15, 2026, per Freddie Mac, does carry a noticeably lower rate than the 30-year. Your monthly payment will be higher because you are compressing the payoff timeline, but you build equity faster and pay substantially less in total interest over the life of the loan.
In my experience, this conversation comes up most often with move-up buyers in Mount Pleasant and West Ashley who are bringing significant equity from a prior home sale. If you are selling a home you bought years ago near Avondale, Byrnes Down, or along Folly Road, you may have enough equity to reduce your new loan balance meaningfully. Running those numbers with your lender to see whether a 15-year makes sense is something I consistently recommend.
This is not a one-size-fits-all decision, though. If you are a first-time buyer stretching to get into a Summerville new construction community, the higher monthly payment on a 15-year may not be realistic. As a Summerville new construction expert, I help buyers evaluate both options in the context of their full financial picture, not just the rate in isolation.
What Charleston Relocation Buyers Should Know About Rate Locks
If you are relocating to Charleston from another state, this rate environment adds another layer of complexity. Many of the buyers I work with are coming from higher-cost markets where they may have sold at a premium and are expecting their dollar to stretch further in the Lowcountry. That is often still true on the home price side, but the borrowing cost has closed some of that gap.
Here is what I see consistently: buyers who are pre-approved but have not yet locked a rate can watch their estimated payment change from one week to the next. A 37-basis-point swing in three weeks, like we just experienced, is not something you can ignore when you are under contract on a home near Shem Creek, in the I’On neighborhood, or along the new construction corridors in Nexton.
Rate locks are your friend in a volatile environment. Talk to your lender about the cost and duration of a lock, and ask about float-down provisions in case rates happen to decline before your closing date. This is standard advice, but it matters more when rates are moving as quickly as they have been this month.
Having closed over 107 transactions, I can tell you that the buyers who come out ahead in environments like this are the ones who plan around the rate they can lock, not the rate they hope for.
Making a Smart Decision in a 7.40% Rate Environment
You might be wondering: should I buy now, or should I wait and hope rates come down? I cannot predict where rates will go, and I would be skeptical of anyone who claims they can. But I can give you an honest framework for making this decision.
Consider these factors:
- Your timeline. If you need to be in Charleston, Mount Pleasant, or Summerville by a specific date for a job, a military PCS, or a family reason, waiting may not be an option.
- Your down payment. A larger down payment reduces your loan amount, which softens the impact of a higher rate. Even a percentage point or two more down can make a noticeable difference in your monthly obligation.
- Refinancing potential. You buy the home at today’s price and today’s rate, but the rate is not permanent. If rates decline in the future, refinancing is an option, subject to costs and qualification at that time.
- Inventory conditions. In some Charleston-area neighborhoods, there may be more negotiating room on price or seller concessions — your agent can advise on current conditions in the specific area you are targeting.
What I always remind my clients: the rate you pay is a cost of borrowing, but the home you buy is a long-term asset. The best decision accounts for both.
Frequently Asked Questions
What is the 30-year fixed mortgage rate this week?
As of October 15, 2026, the national average for a 30-year fixed-rate mortgage is 7.40%, per Freddie Mac’s Primary Mortgage Market Survey. Your individual rate may vary based on credit score, down payment, loan type, and lender. This is a national average, so checking with a local Charleston-area lender for your specific quote is always the right move.
What is the 15-year fixed mortgage rate right now?
The 15-year fixed-rate mortgage averaged 6.71% as of October 15, 2026, according to Freddie Mac PMMS. This is higher than the 6.60% reported the prior week on October 1, 2026. The 15-year can be a strong option for buyers with significant equity, particularly those upsizing in Mount Pleasant.
How much have rates increased this month?
Rates have risen sharply. The 30-year fixed went from 7.03% on September 24, 2026, to 7.40% on October 15, 2026, per Freddie Mac. That is approximately 37 basis points in about three weeks, a pace that directly affects monthly payment estimates for Charleston-area buyers currently shopping.
What were mortgage rates one year ago?
One year ago, as of October 15, 2025, the 30-year fixed averaged 6.27% and the 15-year averaged 5.52%, per Freddie Mac. Today’s rates are 113 and 119 basis points higher, respectively. That year-over-year increase has been a significant affordability factor for buyers across Summerville, Mount Pleasant, and Charleston.
What was the lowest mortgage rate in 2026?
The 30-year fixed hit a calendar-year low of 6.00% during the week of March 5, 2026, per Freddie Mac PMMS. The 15-year low was 5.98% during the week of February 26, 2026. Buyers who locked rates during late winter secured the best terms of the year so far.
How does a 7.40% rate affect my monthly payment?
On a $400,000 loan over 30 years at 7.40%, your principal and interest payment is approximately $2,764 per month. At the 2026 low of 6.00%, that same loan would have been about $2,398 per month, a difference of roughly $366 each month. These are for illustration only and do not include taxes, insurance, or other costs.
Should I wait for rates to drop before buying in Charleston?
Nobody can reliably predict rate movements. What I tell my clients is to focus on the factors you can control: your timeline, your down payment, and your budget. Waiting carries its own risks, including potentially higher home prices or losing out on a property you love. Making a well-informed decision today often beats waiting for a perfect rate that may not arrive.
Is now a good time for first-time buyers in Summerville?
Summerville often offers more accessible price points than Mount Pleasant or downtown Charleston, which can help offset the impact of higher rates. First-time buyers should explore all available assistance programs through their lender, consider the 30-year fixed for lower monthly payments, and work with a Summerville home selling expert or buyer’s agent who understands the local inventory.
Are VA loan rates different from conventional rates?
VA loan rates are set by individual lenders, not the VA itself, and they often differ from conventional rates. With Charleston’s proximity to Joint Base Charleston, VA eligibility is common in this market. If you qualify, a VA loan may offer favorable terms, but you should compare quotes from multiple lenders to find your best option.
Should I lock my rate now or float?
In a rising rate environment like the one we have seen through October 2026, locking your rate provides certainty. Talk to your lender about lock duration, cost, and whether a float-down provision is available. Rated 5.0 out of 5 stars by 33 past clients, I work closely with buyers to coordinate timing between your contract and your rate lock, so nothing falls through the cracks.
The Bottom Line
This week’s rates are the highest recorded in the data points covered here for 2026, and they have climbed fast. The 30-year fixed at 7.40% and the 15-year at 6.71% as of October 15, 2026, per Freddie Mac, represent a very different landscape than what buyers saw earlier this year. But the Charleston, Mount Pleasant, and Summerville markets are still full of opportunity if you approach them with clear eyes and a solid plan.
As a REALTOR and Realtor of Distinction with AgentOwned Realty Charleston Group, I have spent 7 years helping buyers navigate rate environments just like this one. Whether you are relocating to the Lowcountry, buying your first home in Summerville, or moving up in Mount Pleasant, I would rather give you the full picture than a rosy one. That is how you move forward with real confidence. If you want to talk through what this week’s rates mean for your specific situation, reach out to me at 843-714-3806 or visit mynextcharlestonhome.com. Let’s figure out your best path forward together.