What is the process of buying a home in Charleston, SC, and what should Summerville buyers know before getting started?
Buying a home in the Summerville area follows a clear sequence: get financially ready, secure pre-approval, search with a local agent, make an offer, navigate inspections and the attorney-led closing that South Carolina requires, and close on your new home.
Why the Summerville Home Buying Process Matters Right Now
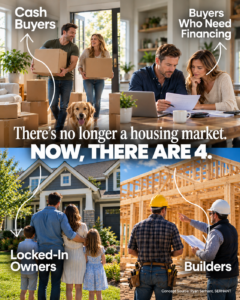
If you have been watching the Charleston-area market, you have probably noticed a shift. According to the Charleston Trident Association of REALTORS®, residential single-family inventory across the entire Charleston Trident MLS reached 4,128 homes for sale as of September 2026, up 9.3% year-over-year. That means you, as a buyer, have meaningfully more choices and negotiating room than you would have had even a year ago.
I have helped many families relocating to Charleston, SC, and one thing I always tell them is this: buying a home in South Carolina is not quite like buying in other states. The climate, the legal requirements, and the inspection standards are all different here. If you are coming from out of state, or even if you are a first-time buyer already living in the Lowcountry, understanding these differences before you start your search will save you time, stress, and potentially thousands of dollars. Let me walk you through every step.
Getting Financially Ready Before You Search in Summerville
Before you even browse a single listing, you need a clear picture of what you can comfortably afford. And “comfortably” is the key word here.
Know Your Real Monthly Cost
The CFPB’s 2026 Home Loan Toolkit recommends that your total monthly housing payment stay at or below 28% of your gross monthly income (per the CFPB, as of August 2026). But that payment is not just principal and interest. In the Summerville area, your total cost includes:
- Principal and interest on your mortgage
- Property taxes (and you should ask your closing attorney about the 4% primary-residence assessment ratio and Homestead Exemption, which South Carolina law requires the closing attorney to provide applications for at closing)
- Homeowner’s insurance
- Flood insurance, which is required if your property sits in a FEMA-designated Special Flood Hazard Area. Portions of Summerville, Charleston, and Mount Pleasant all include these zones.
- HOA fees, which are common in many Summerville neighborhoods and new-construction communities
- Maintenance reserves, because the Lowcountry’s humidity and climate demand proactive upkeep
What does that actually look like for your budget? I always tell my clients to build out a realistic monthly spreadsheet before they fall in love with a house. It keeps the excitement grounded in numbers that work.
Pull Your Credit Early
Your credit score directly affects the interest rate a lender will offer you. Pull your reports early, dispute any errors, and give yourself time to improve your score if needed. Even a small rate difference compounds into thousands over a 30-year loan.
Getting Pre-Approved and Shopping Lenders for Your Summerville Purchase
Pre-approval is not optional in this market. It is the standard expectation from listing agents in Charleston, Mount Pleasant, and Summerville. Without a pre-approval letter, your offer may not even be considered.
Why Multiple Loan Estimates Matter
The CFPB recommends requesting Loan Estimates from at least three lenders before choosing a mortgage (per the CFPB, as of August 2026). A Loan Estimate is a standardized form that every lender must deliver within three business days of your application, and it makes side-by-side comparison straightforward. You are comparing interest rates, closing costs, and loan terms all on the same document format.
In my experience working with over 107 closed transactions, I have seen buyers save meaningful money simply by shopping one or two more lenders than they initially planned. Do not skip this step.
Pre-Approval vs. Pre-Qualification
Pre-qualification is a quick, informal estimate. Pre-approval means the lender has verified your income, assets, and credit and is prepared to lend you a specific amount. In the Summerville market, a strong pre-approval letter signals to sellers that you are serious and financially capable.
Searching for the Right Home in Summerville with a Local Buyer’s Agent
With 4,128 residential single-family homes for sale across the Charleston Trident MLS as of September 2026 (per the Charleston Trident Association of REALTORS®), you have more options than buyers had in recent years. But more inventory also means more decisions, and that is where local knowledge becomes critical.
Why Summerville Attracts Relocating Families
I have helped many families moving to Charleston from out of state, and the appeal makes sense. Compared to the Charleston peninsula and Mount Pleasant, Summerville often offers more space at a lower price point.
As a Summerville new construction expert, I bring a balanced perspective to help you weigh whether a fresh build or an established home with some history is the right fit. Both have advantages, and both come with considerations that a local agent can help you see clearly.
Mount Pleasant: A Tighter Submarket
If you are also considering Mount Pleasant, it is worth knowing that ZIP 29464 in Mount Pleasant had 137 residential single-family homes for sale in September 2026, a 2.1% year-over-year dip (per the Charleston Trident Association of REALTORS®). That submarket remains tighter than the broader region, with inventory down 2.1% year-over-year — buyers should factor this into their search strategy. A Mount Pleasant home buyer expert can help you navigate those dynamics.
What a Local Agent Filters For
A buyer’s agent who knows the Lowcountry will filter your search by factors that national search tools often miss:
- Flood zone designation, which directly impacts insurance costs
- School district boundaries, which can shift from one street to the next
- Commute corridors to employers in North Charleston, downtown, or the tech and medical campuses
- Neighborhood character, which varies enormously even within Summerville itself
Making an Offer and Understanding South Carolina’s Seller Disclosure
Once you find the right home, you will work with your agent to craft a competitive offer. But before you sign the purchase contract, South Carolina law requires something many out-of-state buyers do not expect.
The Seller Disclosure Statement
Under SC Code §27-50, the seller must deliver a Residential Property Condition Disclosure Statement to you before the purchase contract is signed. This document outlines known defects, past repairs, and the current condition of major systems. Read it carefully. It should inform your inspection strategy and may reveal issues worth negotiating before you commit.
Contingencies That Protect You
Your offer will typically include:
- Financing contingency, which protects you if your loan falls through
- Inspection contingency, which gives you the right to renegotiate or walk away based on inspection findings
- Appraisal contingency, in many cases, to ensure the home’s value supports the purchase price
With 7 years of experience and a 5.0 out of 5 star rating across 33 client reviews, I have navigated these negotiations in all kinds of market conditions. I would rather give you the full picture than a rosy one, so you can move forward with real confidence.
Why South Carolina’s Attorney-State Closing Process Changes Everything
Here is the part that catches almost every relocating buyer off guard. Are you coming from a state where a title company or escrow officer handled your last closing? South Carolina works differently.
What “Attorney State” Means for You
South Carolina law requires a licensed SC attorney to be involved in the closing of real estate transactions. Under SC Code §30-5-35, as amended, deeds and mortgages may need to identify the closing attorney in order to be recorded. This is one of the most common surprises I see with buyers relocating from other states. The closing attorney prepares all transfer documents, conducts the title search, and ensures a clean transfer of ownership — your closing attorney can explain the scope of their role and obligations to you specifically.
If you have purchased a home in a Western state, you may be wondering, “Who is this attorney and why do I need one?” The answer is straightforward: they serve a similar function to the title and escrow companies you may be used to, but they are a licensed SC attorney — your closing attorney can explain the scope of their role and obligations to you specifically. Budget for attorney fees as part of your closing costs in South Carolina.
The Closing Disclosure Timeline
At least three business days before closing, you will receive a Closing Disclosure from your lender, per the CFPB’s guidance on owning a home. This document itemizes all final loan terms and fees, and you should compare it carefully against your original Loan Estimate. If something looks different, ask questions immediately. That three-day window exists specifically so you have time to review and raise concerns.
Inspections in the Lowcountry: CL-100, Mold, and Flood Zones in Summerville
This is where buying in the Summerville and greater Charleston area truly differs from buying in most of the country. The Lowcountry’s humid subtropical climate and coastal environment require inspections that buyers from inland states rarely encounter.
The CL-100 Wood Infestation Report
A CL-100 inspection checks for termites and other wood-destroying organisms. It is standard practice in the Lowcountry and often required by lenders. In my experience, this is not something to skip or take lightly. Wood-destroying organisms are a persistent concern in this climate, and catching an issue early can save you from costly structural repairs.
Mold Inspections
Given the humidity levels in Summerville and the broader Charleston area, mold inspections are also common. I recommend them particularly for older homes, homes that have been vacant, or properties near waterways.
Flood Insurance: Required in Certain Summerville Areas
Flood insurance is required for homes in FEMA-designated Special Flood Hazard Areas, and significant portions of Charleston, parts of Mount Pleasant, and some Summerville communities fall within these zones. Before you make an offer, verify the flood zone designation of any property you are considering. Flood insurance premiums can be substantial and will affect your monthly housing cost.
At closing, your lender will require proof of both homeowner’s insurance and flood insurance (where applicable) before funding the loan, per the CFPB.
Frequently Asked Questions About Buying a Home in Summerville and Charleston
How long does it take to close on a home in Summerville, SC?
You should plan for roughly 30 to 45 days from accepted offer to closing in a typical transaction. South Carolina’s attorney-state requirements and the inspection process, including the CL-100 and potential mold inspections, can add time compared to states where escrow companies handle closings. Your agent and closing attorney will coordinate to keep things on track.
Do I need a buyer’s agent to purchase a home in Summerville?
While it is not legally required, working with a local buyer’s agent gives you a significant advantage. With 4,128 homes for sale across the Charleston Trident MLS as of September 2026 (per the Charleston Trident Association of REALTORS®), a local agent helps you filter by flood zone, school district, and neighborhood character in ways that online searches cannot match.
What is a CL-100 inspection and why is it important in the Lowcountry?
A CL-100 is a Wood Infestation Report that checks for termites and other wood-destroying organisms. It is standard in the Summerville and Charleston area due to the humid subtropical climate that makes wood-destroying organisms a persistent concern. Many lenders require this inspection before approving your loan.
Is flood insurance required for all Summerville homes?
Flood insurance is required for homes in FEMA-designated Special Flood Hazard Areas. Not all Summerville homes fall in these zones, but some do. Your agent and lender can help you verify the flood zone designation of any specific property before you make an offer.
What does a closing attorney do in South Carolina?
A licensed SC closing attorney prepares all transfer documents, conducts the title search, ensures a clean title transfer, and oversees the closing. Under SC Code §30-5-35, the closing attorney may need to be identified on the deed for it to be recorded. This role replaces the title company or escrow officer used in many other states.
How many lenders should I get Loan Estimates from?
The CFPB recommends at least three, as of August 2026. Each lender must provide a standardized Loan Estimate within three business days of your application, making side-by-side comparison straightforward. Even small rate differences can save thousands over the life of your loan.
What is the difference between pre-qualification and pre-approval?
Pre-qualification is a quick, informal estimate of what you might borrow. Pre-approval means the lender has verified your income, assets, and credit. In the Summerville market, listing agents expect to see a pre-approval letter with your offer, not just a pre-qualification.
What should my total monthly housing cost be as a percentage of income?
A widely used lending guideline suggests your total monthly housing payment, including taxes, insurance, and HOA fees, should be at or below 28% of your gross monthly income, per the CFPB’s 2026 Home Loan Toolkit.
What is the Seller Disclosure Statement in South Carolina?
Under SC Code §27-50, the seller must provide a Residential Property Condition Disclosure Statement before you sign the purchase contract. This document discloses known defects and the condition of major systems. Use it to guide your inspection decisions and inform your negotiation strategy.
How does the Homestead Exemption work for Summerville buyers?
Your closing attorney can provide you with a Department of Revenue application for the 4% primary-residence assessment ratio and the Homestead Exemption at closing. This can be a meaningful property-tax benefit for owner-occupants. Your closing attorney can explain eligibility requirements specific to your situation.
The Bottom Line on Buying a Home in Summerville
The process of buying a home in the Summerville and greater Charleston area follows a clear path, but it includes steps that buyers from other states often do not anticipate. From the attorney-led closing to the CL-100 inspection to flood insurance requirements, this market has its own rhythm, and understanding it before you start puts you in a stronger position.
With 7 years of experience as a Charleston relocation expert, 107 closed transactions, and a recognized Realtor of Distinction designation, I have walked many families through every stage of this process. My goal is simple: to help you find the right home and make the journey feel as easy as it should be. If you are considering a move to Summerville, Mount Pleasant, or anywhere in the Lowcountry, I would love to be the person who helps you see the full picture. Reach out to me, Irina Bordyn, at 843-714-3806 or visit my website at mynextcharlestonhome.com to start the conversation.