After we sell our Charleston National home in Mount Pleasant, what are the best smaller homes or townhomes available in Summerville, SC, that one person can afford on a single income in 2026?
Summerville offers meaningfully more inventory and lower price points than Mount Pleasant in 2026, and your Charleston National equity can position you to buy a townhome or smaller single-family home comfortably on one income.
Why This Matters Right Now for Charleston National Sellers
If you are going through a divorce and staring at the reality of selling your Charleston National home, I want you to know something: you are not starting over from scratch. You are starting from a position of real equity in one of Mount Pleasant’s most established golf-course communities, and that equity is your bridge to a fresh chapter.
Here is the landscape as of fall 2026. Across the entire Charleston Trident Association of REALTORS (CTAR) MLS, single-family inventory reached 4,133 active listings in September 2026, up 9.4% year over year, per the CTAR MLS Market Monitor. Summerville has seen significant new-construction activity, and with CTAR MLS inventory up 9.4% year over year as of September 2026, buyers relocating there have meaningfully more choices than a year ago. Meanwhile, Mount Pleasant’s ZIP 29464 held just 137 single-family homes for sale that same month, actually down 2.1% from the prior year, per the same CTAR data.
What does this mean for you? Mount Pleasant remains tight, which supports your sale price. Summerville is expanding, which gives you more choices and less competition on the buy side. That is the exact combination a single-income buyer needs in 2026.
How Your Charleston National Equity Becomes Summerville Buying Power
The single biggest question I hear from clients navigating a divorce sale is, “Can I actually afford anything on just my income?” In most cases, when you are selling out of a community like Charleston National in Mount Pleasant, the answer is a reassuring yes, and here is why.
Charleston National homes have historically commanded prices well above the Charleston metro median. Even after splitting proceeds with your former spouse, paying off the remaining mortgage balance, covering South Carolina deed recording fees, and handling closing costs, many sellers walk away with substantial equity. That equity becomes your down payment on a Summerville property.
Why does the down payment matter so much? Because it directly reduces your monthly mortgage payment, which is the number your lender cares about when they calculate your debt-to-income ratio. A larger down payment means a smaller loan, which means a lower monthly obligation, which means you can qualify even though your household income has been cut roughly in half.
For illustration purposes: if you earn $75,000 per year as a single buyer (roughly $6,250 per month gross) and your lender uses a 43% debt-to-income ceiling, your maximum total monthly debt service would be approximately $2,688. With a substantial down payment from your Charleston National equity, a Summerville townhome payment could fit well within that number. Note that actual qualification depends on your credit score, existing debts, and lender-specific overlays, so working with a mortgage professional early is essential.
One Critical Step Before You Start Shopping in Summerville
Your Charleston National sale needs to close, or at minimum, you need a signed divorce settlement agreement that releases you from the joint mortgage obligation, before most lenders will exclude that payment from your debt-to-income calculation. I always tell my clients: do not try to carry two housing costs simultaneously. A brief rental period or a carefully structured contingency offer protects you from financial strain during the transition.
Summerville Neighborhoods Worth Touring on a Single Income in 2026
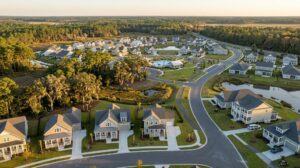
Summerville’s appeal for someone stepping down from a larger Mount Pleasant home is not just about price. It is about lifestyle. These master-planned communities offer low-maintenance living, community amenities, and a sense of belonging that matters when you are rebuilding your daily routine.
Nexton in Summerville
Nexton is one of the most recognized master-planned communities in the Summerville area, and it includes a range of townhome and smaller single-family options. The community is designed around walkability, with shops, restaurants, and green spaces integrated into the neighborhood. For someone who has been living in a larger Charleston National home and managing it alone, the built-in community feel at Nexton can be genuinely restorative.
Cane Bay Plantation
Cane Bay Plantation in Summerville has grown into one of the largest master-planned developments in the region, with builders offering attached and smaller detached homes at various price points. The community includes trails, pools, and gathering spaces, and you will find new construction options that fit a single-income budget.
The Ponds in Summerville
The Ponds sits within the Summerville area and offers a charming, almost village-like atmosphere with townhomes and cottage-style homes. If you are someone who loved the character of Charleston National’s established streetscapes, The Ponds’ design may appeal to that same aesthetic sensibility.
Carnes Crossroads
Straddling the Goose Creek and Summerville border, Carnes Crossroads has added significant attached-home inventory in recent years. Its walkable layout and emphasis on community make it another strong candidate for a single buyer who wants neighbors and connection without the burden of maintaining a large property.
In my experience as a REALTOR specializing in new construction, I find that touring these communities in person changes the way many buyers feel about their next chapter. What looks like “downsizing” on paper often feels like upgrading your quality of life when you walk through the door.
Why Townhomes in Summerville Make Sense for a Post-Divorce Fresh Start
Let me be straightforward about why I steer many of my single-income clients toward townhomes, especially in the Summerville market.
Lower purchase price relative to detached homes. Summerville’s townhome segment, concentrated in ZIPs 29483 and 29485, is widely regarded by local agents and buyers as offering a more attainable entry point than detached single-family homes in the same areas. That gap matters enormously when you are qualifying on one income.
Reduced maintenance burden. When you are handling everything yourself, from yard work to roof repairs, that workload adds up. Many Summerville townhome communities include exterior maintenance and landscaping within the HOA fee. You pay a predictable monthly amount and reclaim your weekends.
Built-in community. After a divorce, isolation is a real risk. Townhome communities tend to foster more neighbor interaction simply through proximity and shared amenities. That social fabric can be a genuine support system during a difficult transition.
Preserving your equity cushion. Buying a less expensive property means you do not have to pour every dollar of your Charleston National proceeds into the down payment. Keeping a financial reserve gives you breathing room for unexpected expenses, which is critical when you no longer have a second income to fall back on.
Having closed over 107 transactions and earned a Realtor of Distinction recognition, I have walked many buyers through this exact decision. The consistent feedback I receive is that choosing a townhome felt like lifting a weight, not settling for less.
Financial Steps to Take Before Buying in Summerville After Selling in Mount Pleasant
The period between selling your Charleston National home and buying in Summerville involves several financial steps that, if handled in the right order, make the entire process smoother.
Step 1: Finalize your divorce settlement before listing. Your settlement agreement determines how proceeds from the Charleston National sale will be divided. Without that clarity, you cannot accurately calculate your available down payment. Your divorce attorney and your REALTOR should be in communication early.
Step 2: Get pre-approved on your individual income. Lenders evaluate your qualification based on your personal income, credit score, and debts. They do not penalize you for being divorced. What matters is that the joint mortgage on the Charleston National property is either paid off through the sale or formally released from your responsibility. I always recommend that my clients connect with a mortgage professional before we even start looking at Summerville listings.
Step 3: Understand South Carolina closing costs on both sides. South Carolina imposes a deed recording fee (deed stamps) on real property transfers, and you will encounter them on the Mount Pleasant sale. Your closing attorney will clarify which fees apply on the Summerville purchase side, but budgeting for closing costs on both transactions upfront prevents surprises. Your closing attorney will itemize these, but budgeting for them upfront prevents surprises. This is the kind of detail that falls through the cracks when you are emotionally overwhelmed, which is exactly why I stay close to every step of the process.
Step 4: Consider a temporary rental if timing does not align. If your Charleston National home sells before you have found the right Summerville property, a short-term rental protects you from making a rushed decision. Summerville’s growing inventory, which was up across the CTAR MLS by 9.4% year over year as of September 2026, per the CTAR Market Monitor, means you have more options than buyers had even a year ago. Give yourself the time to choose well.
How Summerville’s 2026 Market Conditions Favor Single-Income Buyers
The 2026 market conditions offer a meaningful advantage for buyers making this move. Here is what has shifted in your favor.
The entire CTAR MLS held 4,133 active single-family listings in September 2026, representing a 9.4% increase over the prior year, per the CTAR MLS Market Monitor.
More listings on the market means less bidding-war pressure. For a single-income buyer who cannot afford to stretch beyond a carefully calculated budget, that reduced competition is genuinely meaningful. You are more likely to negotiate favorable terms, request seller concessions toward closing costs, or simply take a breath and make a thoughtful decision rather than a panicked one.
Meanwhile, back in Mount Pleasant, inventory actually tightened slightly. ZIP 29464 saw a 2.1% decline in active listings from September 2025 to September 2026, per the same CTAR data.
So the math works in both directions: you sell in a tight market and buy in an expanding one. That is a rare alignment, and it favors you right now.
Frequently Asked Questions
Can I buy a Summerville townhome before my Charleston National home sells?
It is possible through a contingency offer or a bridge loan, but most lenders will want the joint mortgage on your Charleston National home resolved before fully qualifying you on a single income. In my experience, timing the transactions carefully with your REALTOR and lender is far less stressful than trying to carry two properties simultaneously.
Do I need a REALTOR who knows both Mount Pleasant and Summerville?
Absolutely. Both areas fall within the CTAR MLS, so the listing data is accessible to any licensed agent, but local knowledge of Charleston National’s pricing dynamics and Summerville’s neighborhood nuances makes a significant difference. With 7 years of experience across Charleston, Mount Pleasant, and Summerville, I work both markets regularly.
What is the advantage of new construction in Summerville for a single buyer?
New construction often comes with builder warranties covering major systems for several years, which reduces your risk of unexpected repair costs. As someone who specializes in new construction in Summerville, I can tell you that builders in the Summerville area offer a range of townhome floor plans that work well for single-occupant or small-household living.
Will my divorce affect my ability to get a mortgage in Summerville?
Lenders evaluate you on income, credit, and debts, not marital status. The key is ensuring your name is removed from the Charleston National mortgage through the sale or your settlement agreement. Once that liability is cleared, you qualify as an individual buyer.
How much of my Charleston National equity should I put toward a Summerville down payment?
This depends on your comfort level and financial goals. A larger down payment lowers your monthly payment and may help you avoid private mortgage insurance, but keeping some proceeds in reserve for emergencies is equally important. A mortgage advisor can help you model different scenarios.
Are Summerville HOA fees expensive for townhomes?
HOA fees vary by community and cover different things. In many Summerville townhome communities, the fee covers exterior maintenance, landscaping, and shared amenities. I encourage buyers to request the full HOA budget and reserve study before making an offer so there are no surprises.
How long does it typically take to sell a home in Charleston National?
Can I use FHA financing for a Summerville townhome?
FHA loans are available for qualifying properties, and they allow debt-to-income ratios up to approximately 57% in some cases, which can be helpful for single-income buyers. The townhome community must be FHA-approved, so your lender will verify that during pre-approval.
Should I rent in Summerville first before buying?
A brief rental period can be wise, especially if your divorce is still being finalized or if you want time to explore Summerville neighborhoods before committing. The 2026 inventory growth in the CTAR MLS means you are unlikely to miss out on options by taking a few extra months.
What makes Summerville more affordable than Mount Pleasant for single buyers?
Summerville’s townhome and smaller single-family segment is widely regarded as one of the more attainable price points in the Charleston metro, and the area’s new-construction activity has added supply that moderates pricing pressure. Combine that with the equity you bring from a Charleston National sale, and the numbers tend to work favorably for a single-income buyer.
The Bottom Line for Charleston National Sellers Moving to Summerville
You are not just selling a house. You are closing one chapter and writing the first page of the next one. The equity you have built in your Charleston National home gives you real buying power in Summerville’s expanding market, where townhomes and smaller single-family homes offer comfortable, low-maintenance living that fits a single income.
With 33 five-star reviews and 7 years of experience helping buyers and sellers across Charleston, Mount Pleasant, and Summerville, I have guided people through exactly this kind of transition. I believe real estate is about people first, properties second, and that is especially true when life is asking you to make hard decisions.
If you are ready to explore what Summerville looks like for your next chapter, or if you simply want an honest conversation about what your Charleston National home might net and how far those proceeds can take you, I am here. You can reach me, Irina Bordyn, REALTOR with AgentOwned Realty Charleston Group, at 843-714-3806 or through my website at mynextcharlestonhome.com. Let’s find you a home that feels like yours.